Yes, cash buyers in Dubai are generally less directly affected by interest rate changes because they have no mortgage to reprice, but they are not unaffected. Rates still influence their decisions through opportunity cost, shifts in overall property demand, and changing conditions for mortgage buyers who also shape market pricing and negotiation dynamics.
Are Cash Buyers in Dubai Less Affected by Interest Rate Changes?
Roughly a large share of Dubai property transactions are completed in cash, without any mortgage at all. It's tempting to assume these buyers are simply immune to Federal Reserve and CBUAE rate decisions. That's not accurate. Cash buyers are affected differently, not left untouched — through opportunity cost and market-wide dynamics rather than a monthly payment.
The mortgage buyer's exposure vs. the cash buyer's exposure
A mortgage buyer feels a rate change directly: a variable, EIBOR-linked loan reprices at its next reset, and a new fixed-rate loan is priced off current market rates. A cash buyer has no loan to reprice. Their exposure runs through a different channel entirely: opportunity cost.
What "opportunity cost" means here
Every dirham or dollar a cash buyer puts into a Dubai property is a dirham not earning the return available elsewhere. When interest rates are high, safe, liquid alternatives — UAE bank fixed deposits, US Treasuries, money market instruments — offer a higher risk-free return than they did when rates were low. That raises the bar a property investment has to clear to look attractive on a risk-adjusted basis. When rates fall, that bar lowers, and real assets like property can look comparatively more attractive to cash-rich investors searching for yield.
Why this still shows up in Dubai property demand
Even though no individual cash buyer is repricing a loan, in aggregate this opportunity-cost effect can influence how much cash-buyer demand is in the market at any given time. A period of high risk-free rates can see some cash buyers content to hold deposits rather than deploy capital into property; a period of falling rates can see the reverse. This is a market-wide sentiment effect, not a mechanical, individual payment effect — see Article 1 for how this fits into the full transmission chain.
Why cash buyers still care about mortgage-buyer conditions
Cash buyers are not shopping in a market populated only by other cash buyers. Mortgage-dependent buyers make up a meaningful share of overall demand, and if higher rates are pressuring their affordability, that can affect the pool of active buyers and, over time, price negotiation dynamics in specific market segments — even for a property a cash buyer is purchasing outright. See Article 12 for the evidence on how (and how much) demand shifts actually show up in prices.
Where cash buyers have a genuine structural advantage
Cash buyers are not exposed to reset risk (a variable-rate mortgage repricing higher), qualification risk (a bank tightening lending criteria as rates rise), or the compounding effect of rate changes on total interest paid over a loan's life. They also move faster in transactions, since there is no financing approval to wait on — a real advantage in a competitive market regardless of the interest rate environment.
What this means in practice
A cash buyer evaluating a Dubai property in a high-rate environment should compare the property's expected total return (rental yield plus any price appreciation, without assuming a specific future price) against the yield available on safe alternatives right now — not against a mortgage rate that doesn't apply to them. See Article 10 for the specific math behind unleveraged returns, and Article 15 for how this fits into a complete investment decision framework.
Sources & Data
This article describes a general economic mechanism (opportunity cost) rather than citing a specific data point. For current risk-free rate benchmarks, see the Central Bank of the UAE's own data and the US Treasury's daily yield curve rates.
Mechanisms described are general economic principles, current as of September 2026. No forecast of future Dubai property performance is implied.
Muhalab Adam — Real Estate Investment Strategist, Dubai. I help investors evaluate Dubai property using market data.
Want to see how your own numbers compare, cash or financed? Request a free investor consultation.
Sources & Official References
- governmentDubai Land Department (DLD)
- governmentUAE Government Portal — Property & Housing
Frequently Asked Questions
Related Listings

Exclusive Freehold Villa Plot in Dubai Hills Estate | Ready-to-Build with Approved G+1 Design
Emaar (Dubai Hills Estate) · Dubai Hills Estate, Dubai
AED 18,362,500
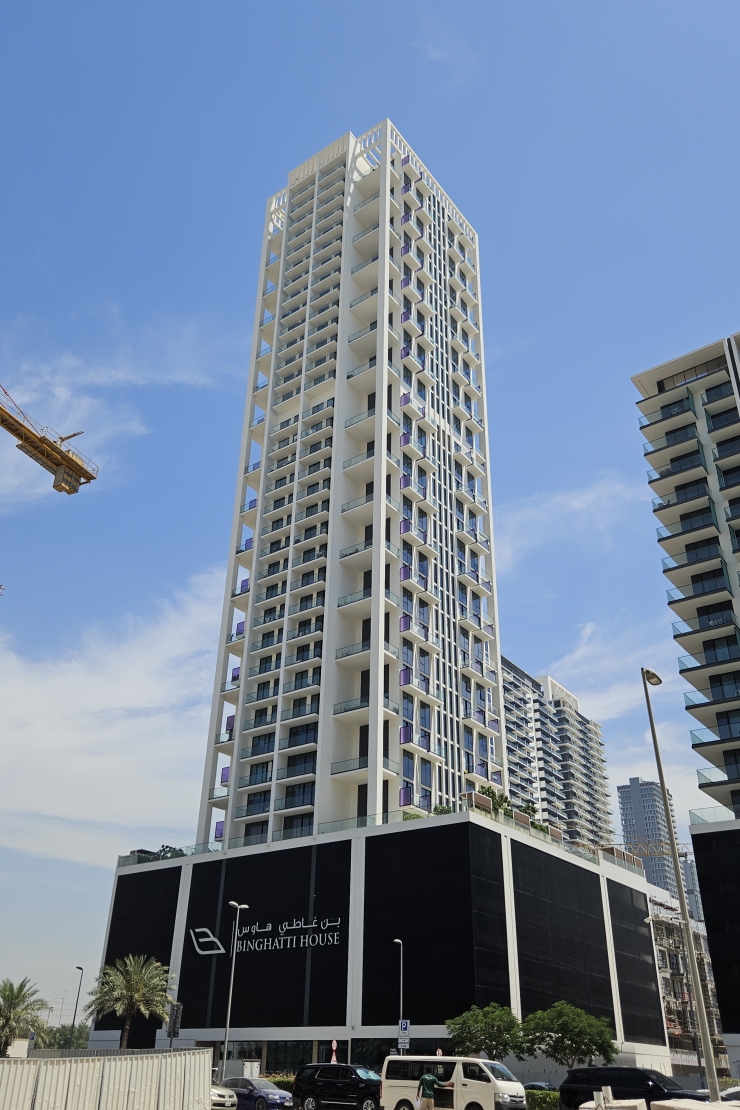
Binghatti House | 2BR Apartment | in JVC | HOT
Binghatti · JVC
1,605,000 AED
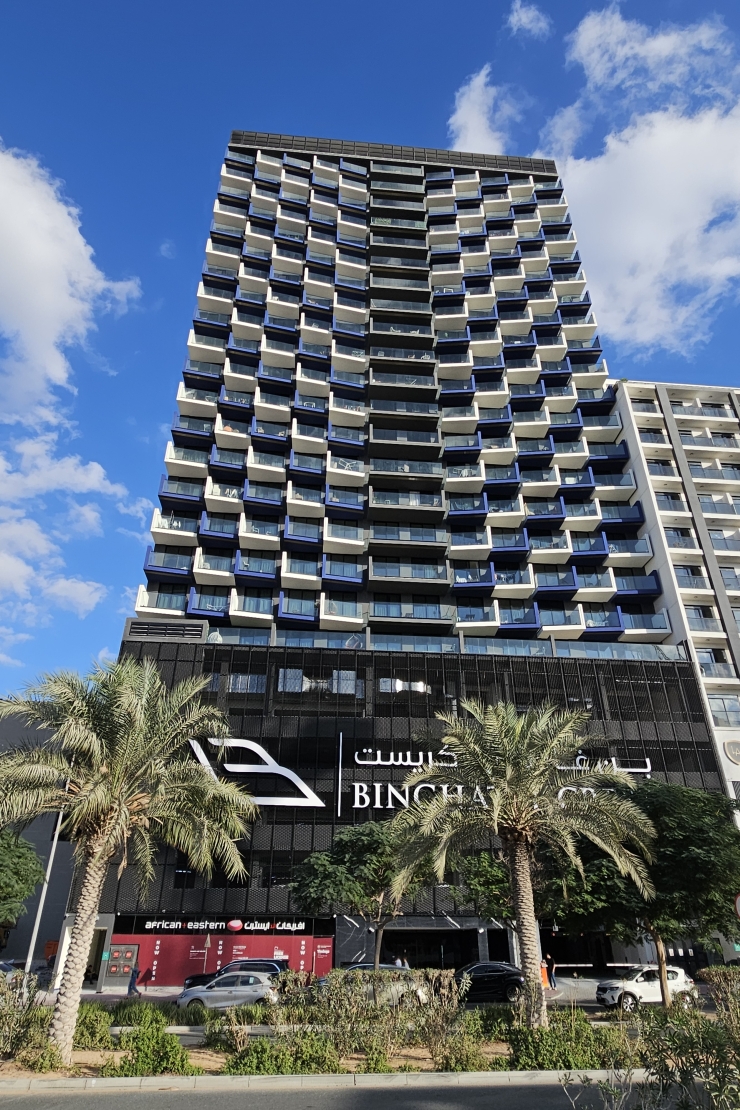
Binghatti Crest | 3BR Apartment | in JVC | HOT
Binghatti · JVC
1,800,000 AED (Furnished)
Equiti Home | 1BR Apartment | in Al Furjan | HOT
BNH Real Estate · Al Furjan
970,000 AED
FIVE Luxe Hotel & Residence | 5BR + Maid Hotel Apartment | in JBR | HOT
FIVE Holdings · JBR
25,000,000 AED / 25,000,000 AED (Furnished)
Azizi Gardens | 1BR Apartment | in Meydan MBR | HOT
Azizi · Meydan MBR
930,000 AED
Match My Requirement
Tell us your budget and preferences — we'll match you with live Dubai & Abu Dhabi inventory within 24h.
Related Articles
Off-Plan Property Investment in Dubai: The Real Numbers Before You Commit
Off-plan property investment in Dubai — real ROI math, launch-phase entry, assignment strategy, and the risks nobody puts in the brochure.

Buying a House Off Plan in Dubai: A Step-by-Step Guide for 2026
Buying a house off plan in Dubai — real step-by-step process, developer payment plans, DLD Oqood registration, fees, and the mistakes that cost buyers real money.
Townhouse vs Villa in Dubai: The Investor and Buyer's Decision Guide
Townhouse or villa in Dubai? A clear comparison covering price, size, maintenance, rental yield, and which communities offer each — written for buyers and investors.