Investors should analyze Dubai property with a 16-point framework that treats interest rates as one important input, not the only decision factor. The key test is whether the investment still works on your actual financing, net rental income, holding period, supply risk, and stress-tested assumptions if rates rise or rents underperform.
How Investors Should Analyze Dubai Property When Interest Rates Are Changing
This is the article every other piece in this series has been building toward. Interest rates are one real, important input into a Dubai property investment decision — but only one. This 16-point framework places interest rates alongside everything else a careful investor should weigh, without recommending any specific property, financing structure, or leverage ratio.
1. Your financing structure (cash vs. leveraged)
Determine whether you are buying in cash or with a mortgage before anything else, since this determines which parts of this framework — and which earlier articles in this series — apply most directly to you. Cash buyers should revisit Article 9; leveraged buyers should revisit Article 5 and Article 10.
2. The actual mortgage rate available to you today
Not a headline rate — the specific rate a specific bank will actually offer you, given your income, credit profile, and the property in question. Get this in writing before running any other calculation.
3. Fixed vs. variable rate structure
Understand whether you're locking a rate for a fixed period or exposed to EIBOR resets (see Article 18), since this determines your exposure to future rate changes over your holding period.
4. Your total financing cost over the expected holding period
Not just the current monthly payment — model what happens to your payment if a variable rate resets higher, using the mechanics in Article 5.
5. Actual comparable rental yields for the specific property and area
Use current, achieved rents for genuinely comparable units — not aspirational listing prices — as covered in Article 11.
6. Realistic vacancy and management costs
Net rental income, not gross, is what belongs in your return calculation. Vacancy periods, management fees, service charges, and maintenance all reduce the yield you actually realize.
7. Leveraged vs. unleveraged return on your actual numbers
Run the arithmetic from Article 10 using your own actual purchase price, actual financing terms, and actual expected rental income — not the illustrative figures in that article.
8. Opportunity cost of your capital (cash buyers especially)
Compare your expected total return against what your capital could earn in safe alternatives right now, per the framework in Article 9.
9. Off-plan vs. ready property considerations
If considering off-plan, understand the payment plan structure and how it compares to a traditional mortgage under current rate conditions — see Article 16 and Article 17.
10. Developer and project track record
Independent of interest rates entirely: does this developer have a track record of on-time, on-quality delivery? This matters as much in any rate environment.
11. Location-specific supply pipeline
How much new supply is scheduled for delivery in this specific area or building type over your holding period? Oversupply risk is a location-specific question, not a citywide interest-rate question.
12. Your own holding period and exit strategy
A short holding period increases sensitivity to near-term price and rate volatility; a longer holding period allows more time for rental income to compound and for rate cycles to turn.
13. Currency exposure if you are an international buyer
If your income or wealth is denominated in a currency other than USD/AED, understand how currency movements — separate from interest rates — affect your real return, per the global capital dynamics in Article 14.
14. Tax and regulatory treatment in your home jurisdiction
Interest rates are a UAE/US question; tax treatment of foreign real estate income and gains is a question for your home country's rules, and it can materially change your net return.
15. Diversification within your broader portfolio
How does this specific property fit alongside your other assets? An investment can make sense for portfolio-diversification reasons independent of whether current interest rates are historically high or low.
16. What actually needs to be true for this investment to work
State explicitly, in writing, what rental yield, financing cost, and holding period assumptions this investment depends on — then stress-test what happens if financing costs rise further, rents come in lower than expected, or your holding period extends. This is the single most useful discipline in this entire framework: know your assumptions before you're relying on them.
What this framework is not
This is not a substitute for professional financial, tax, or legal advice specific to your situation. It is not a prediction of Dubai property performance. It is not a recommendation to buy, wait, or use any particular amount of leverage. It is a structured way to make sure interest rates — a real and important factor — take up their appropriate share of your decision, rather than crowding out the other 15 factors that matter just as much.
Sources & Data
This is a decision framework, not a data-driven forecast. For the underlying evidence referenced throughout, see Article 12 (Dubai price data), Article 11 (Dubai rental data), and the sources cited in each linked article above.
This article does not constitute financial or investment advice. Consult licensed financial, tax, and legal advisors for guidance specific to your situation. Figures and mechanisms current as of September 2026.
Muhalab Adam — Real Estate Investment Strategist, Dubai. I help investors evaluate Dubai property using market data.
Want to work through this framework on a specific property or budget? Request a shortlist of Dubai properties based on your budget, financing structure and investment strategy.
Sources & Official References
- governmentDubai Land Department (DLD)
- governmentUAE Government Portal — Property & Housing
Frequently Asked Questions
Related Listings

Exclusive Freehold Villa Plot in Dubai Hills Estate | Ready-to-Build with Approved G+1 Design
Emaar (Dubai Hills Estate) · Dubai Hills Estate, Dubai
AED 18,362,500
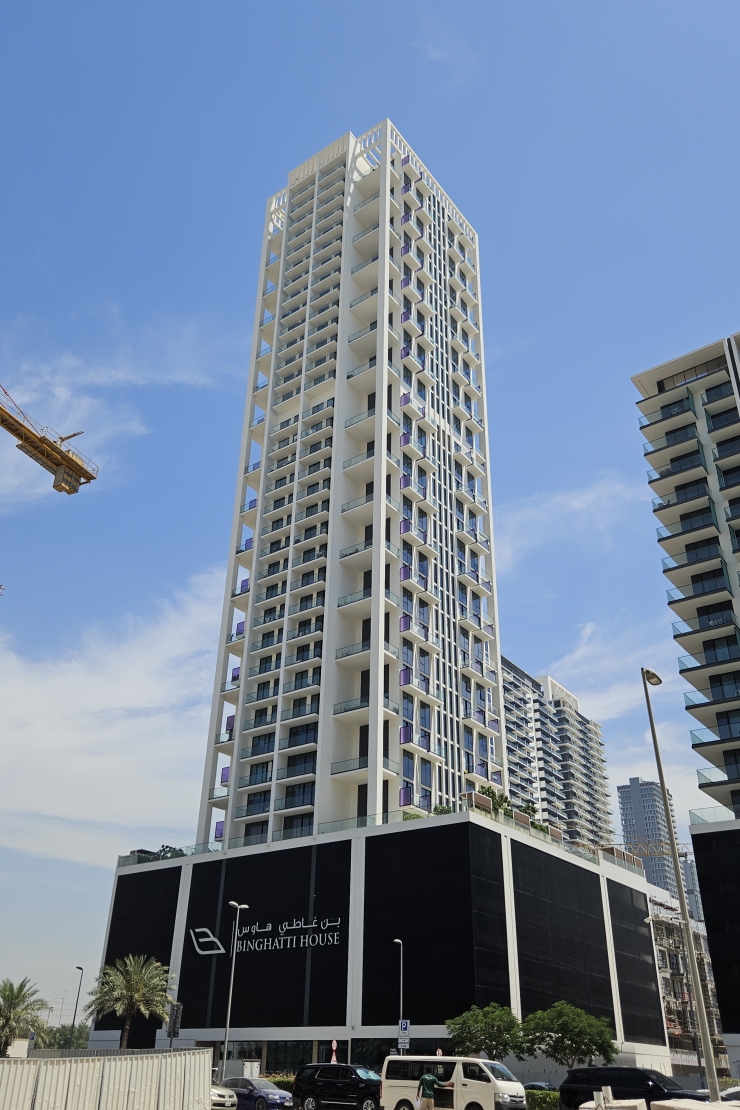
Binghatti House | 2BR Apartment | in JVC | HOT
Binghatti · JVC
1,605,000 AED
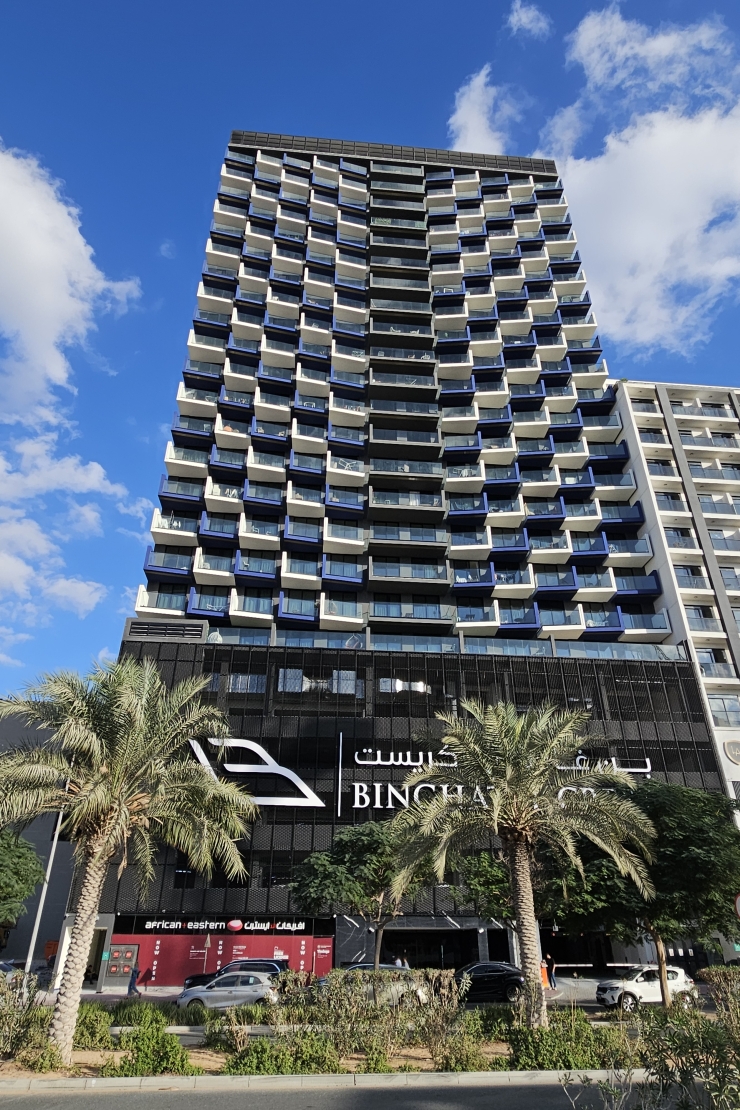
Binghatti Crest | 3BR Apartment | in JVC | HOT
Binghatti · JVC
1,800,000 AED (Furnished)
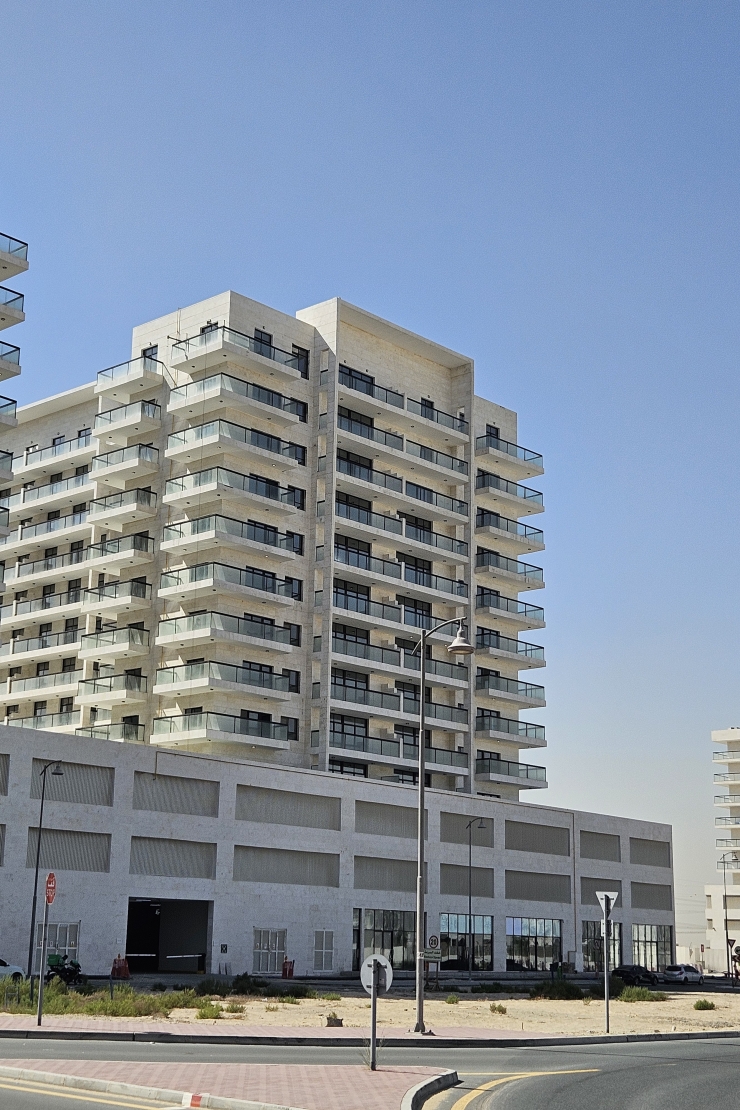
Equiti Home | 1BR Apartment | in Al Furjan | HOT
BNH Real Estate · Al Furjan
970,000 AED
FIVE Luxe Hotel & Residence | 5BR + Maid Hotel Apartment | in JBR | HOT
FIVE Holdings · JBR
25,000,000 AED / 25,000,000 AED (Furnished)
Azizi Gardens | 1BR Apartment | in Meydan MBR | HOT
Azizi · Meydan MBR
930,000 AED
Match My Requirement
Tell us your budget and preferences — we'll match you with live Dubai & Abu Dhabi inventory within 24h.
Related Articles
UAE Rate Hike to 3.90%: What Actually Changes for Dubai Property Buyers?
The UAE Central Bank raised its base rate to 3.90% after the Fed hike. Who is actually affected in Dubai property, and how much does it add to a mortgage payment?
Who Should Buy in Dubai Creek Harbour — and Who Should Think Twice?
A profile-based framework — end users, rental investors, long-term investors, lifestyle buyers, cash and mortgage buyers — for deciding if Creek Harbour fits you.
Which Dubai Creek Harbour Project Should You Consider?
A decision matrix — not a ranking — for choosing between Dubai Creek Harbour projects based on budget, unit size, view, rental strategy and holding period.