Dubai real estate can react differently from US real estate when rates change because Dubai has more cash buyers, more international capital, a mixed mortgage structure, and a large off-plan pipeline with developer payment plans. The same Fed move affects both markets, but Dubai is less uniformly driven by mortgage rates than the US.
Why Dubai Real Estate Can Behave Differently From US Real Estate When Rates Change
Both markets ultimately trace back to the same Federal Reserve decisions. Yet a Fed rate hike that clearly cools a US housing market can coincide with continued strength in Dubai. This is not a contradiction — it reflects genuine structural differences in how each market is financed and who is buying.
Financing mix: the single biggest difference
The US mortgage market is overwhelmingly dominated by financed purchases, with the 30-year fixed-rate mortgage as the standard product. Nearly every US homebuyer's monthly payment is directly, immediately shaped by prevailing mortgage rates. Dubai has a meaningfully higher share of all-cash transactions (see Article 9) alongside mortgage-financed purchases. A market with a larger cash-buyer segment feels a rate-driven affordability squeeze less uniformly than one where financing dominates.
Buyer composition: local vs. international capital
US real estate demand is driven overwhelmingly by domestic buyers subject to domestic income and credit conditions. Dubai draws a substantial share of demand from international buyers and investors — from the GCC, South Asia, Europe, Russia, and elsewhere — whose purchasing decisions are shaped by capital flows, currency dynamics in their home markets, and portfolio diversification objectives, not only by UAE mortgage rates. See Article 14 for how global capital flows interact with Fed policy independently of the direct mortgage-rate channel.
Mortgage structure: fixed-rate dominance vs. a mixed market
The classic 30-year fixed-rate US mortgage locks in a payment for decades, which means existing US mortgage holders are largely insulated from a rate hike (a well-documented "lock-in effect" that also reduces the supply of existing homes for sale). UAE mortgages more commonly involve shorter fixed periods followed by EIBOR-linked variable rates (see Article 18), meaning Dubai borrowers can feel a rate change more directly at their next reset, even as new UAE buyers face different qualifying conditions than new US buyers.
Supply dynamics: a maturing market vs. new master-planned communities
US housing supply is largely an existing-home resale market with comparatively slow new construction relative to demand in many metro areas. Dubai's market includes a very large, continuously replenished off-plan and new-launch pipeline (see Article 16), with developer payment plans (Article 17) offering an alternative financing path that doesn't depend on a bank mortgage rate at all. This gives Dubai's supply side a different sensitivity to interest rates than a supply-constrained US metro area.
Tax and yield structure
The absence of property tax and capital gains tax on real estate in the UAE changes the after-tax return calculation for both cash and leveraged investors compared to most US markets, which can maintain investor demand even when gross yields compress.
What this means for a Dubai investor watching US news
US real estate headlines about Fed rate hikes cooling the housing market are describing a market with a fundamentally different financing structure, buyer base, and supply dynamic than Dubai's. They are useful context for understanding the same underlying Fed decision, but they are not a reliable predictor of what happens in Dubai specifically. See Article 12 for the evidence-based look at what actually happens to Dubai prices when rates change.
Sources & Data
- Federal Reserve — FOMC statement, September 16, 2026
- Dubai Land Department — News & Media
- Central Bank of the UAE — press release index
This article compares general market structures rather than predicting relative performance of either market. Figures current as of September 2026.
Muhalab Adam — Real Estate Investment Strategist, Dubai. I help investors evaluate Dubai property using market data.
Want to understand what changing interest rates could mean for your Dubai property strategy? Request a free investor consultation.
Sources & Official References
- governmentDubai Land Department (DLD)
- governmentUAE Government Portal — Property & Housing
Frequently Asked Questions
Related Listings

Exclusive Freehold Villa Plot in Dubai Hills Estate | Ready-to-Build with Approved G+1 Design
Emaar (Dubai Hills Estate) · Dubai Hills Estate, Dubai
AED 18,362,500
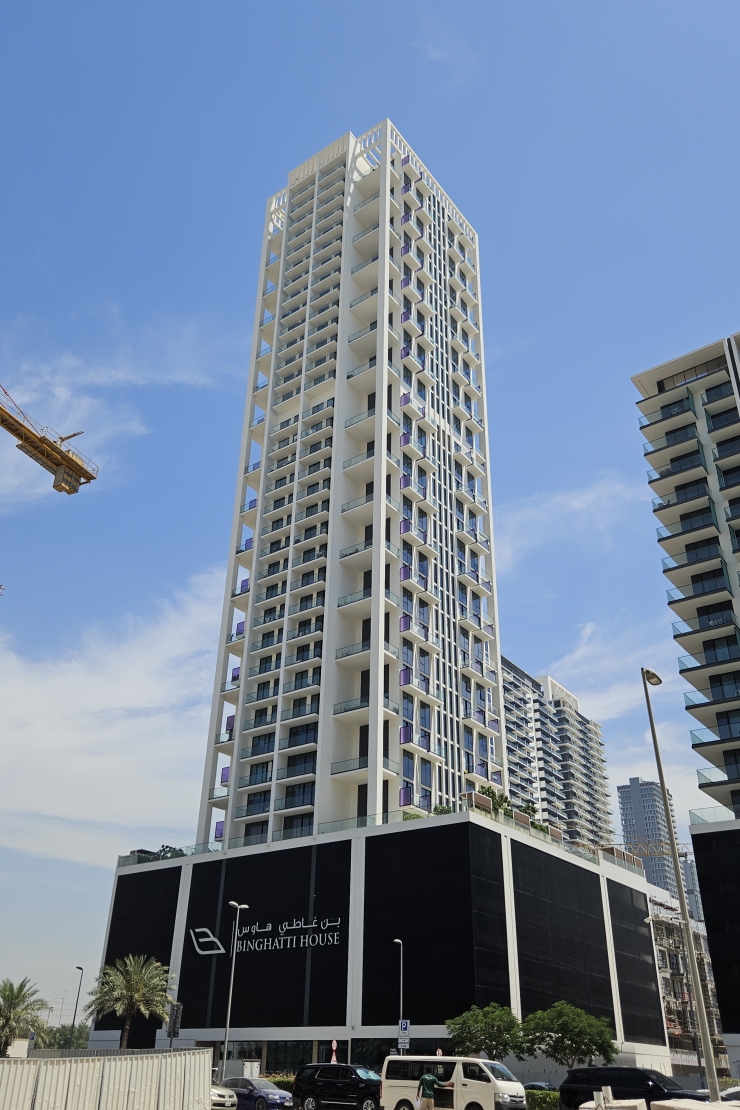
Binghatti House | 2BR Apartment | in JVC | HOT
Binghatti · JVC
1,605,000 AED
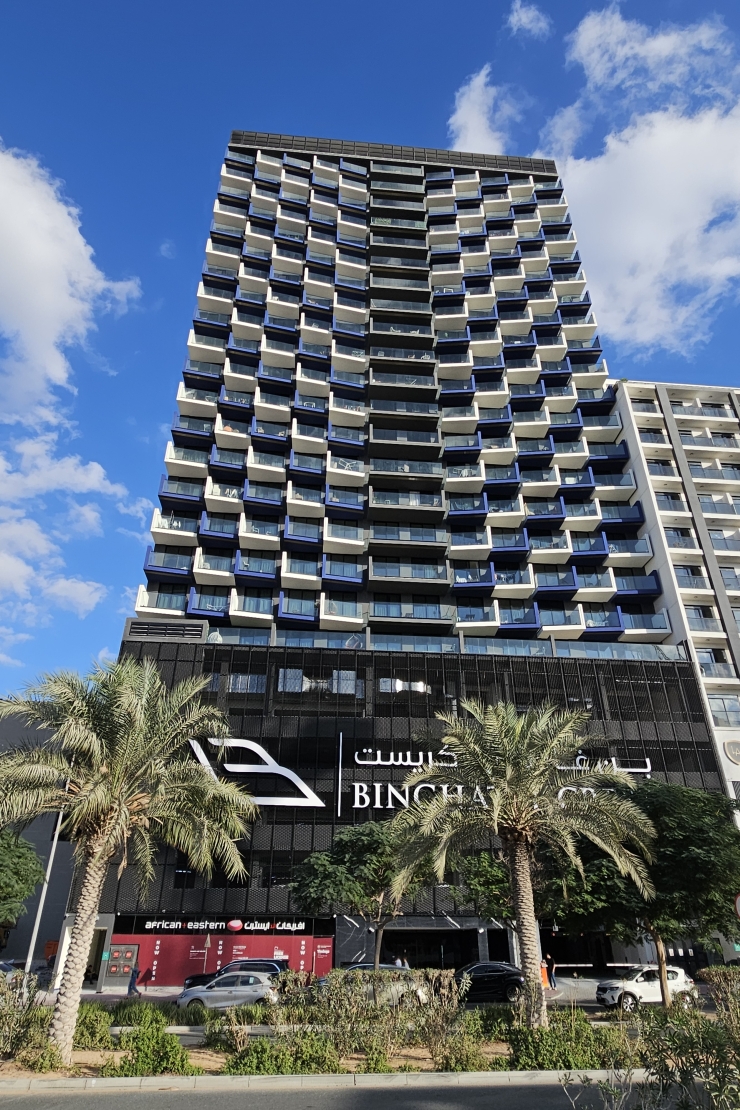
Binghatti Crest | 3BR Apartment | in JVC | HOT
Binghatti · JVC
1,800,000 AED (Furnished)
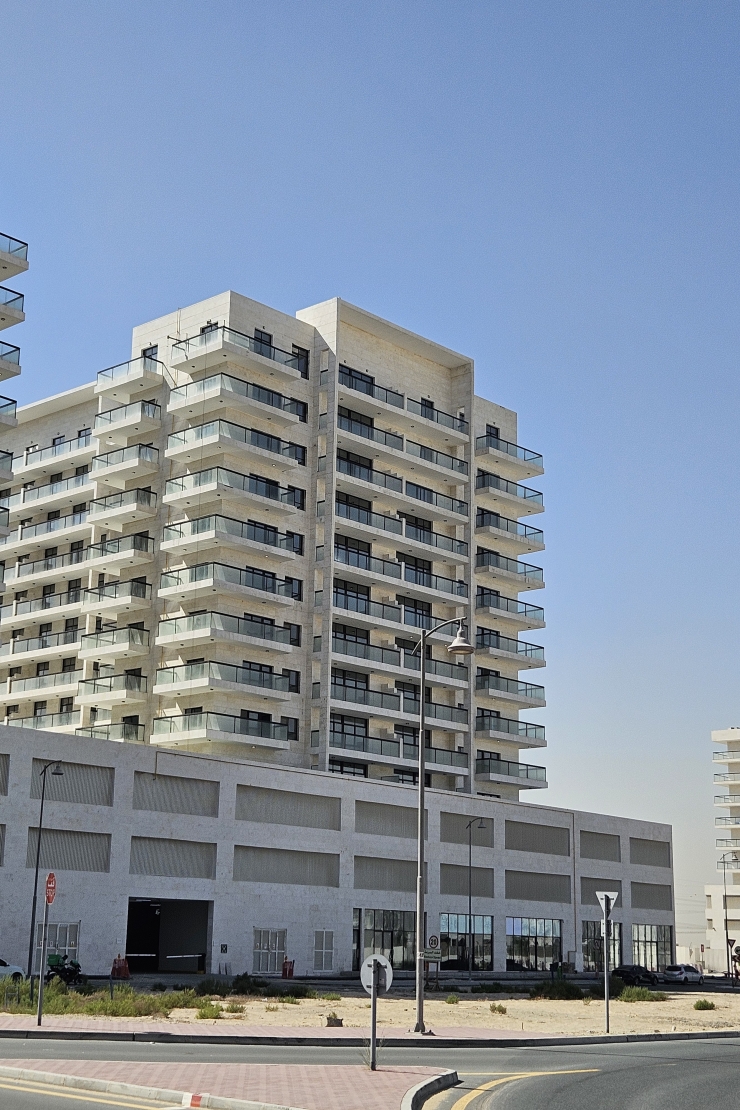
Equiti Home | 1BR Apartment | in Al Furjan | HOT
BNH Real Estate · Al Furjan
970,000 AED
FIVE Luxe Hotel & Residence | 5BR + Maid Hotel Apartment | in JBR | HOT
FIVE Holdings · JBR
25,000,000 AED / 25,000,000 AED (Furnished)
Azizi Gardens | 1BR Apartment | in Meydan MBR | HOT
Azizi · Meydan MBR
930,000 AED
Match My Requirement
Tell us your budget and preferences — we'll match you with live Dubai & Abu Dhabi inventory within 24h.
Related Articles
UAE Rate Hike to 3.90%: What Actually Changes for Dubai Property Buyers?
The UAE Central Bank raised its base rate to 3.90% after the Fed hike. Who is actually affected in Dubai property, and how much does it add to a mortgage payment?
Federal Reserve Interest Rates in 2026: What Dubai Property Investors Need to Watch
A living hub tracking every Fed decision through 2026 and what it means for Dubai real estate — updated after every FOMC meeting.
What Is EIBOR and Why Does It Matter to Dubai Property Investors?
EIBOR is the benchmark that actually prices most variable-rate mortgages in the UAE — and it's not the same thing as the Fed's rate or the CBUAE Base Rate. Here is how it works.